Builders Risk Insurance
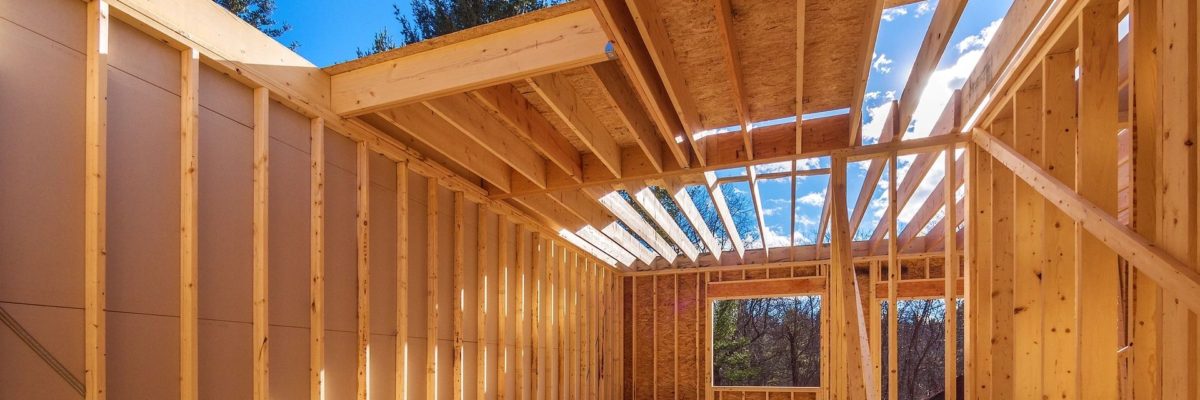
Builder’s risk insurance is a policy designed to mitigate the chance of loss and protect you in the event that damage is done to the building. While fire, floods, and vandalism pose a threat to a constructed building, buildings under construction aren’t ready to face risks that completed buildings can withstand. A proper risk analysis from our Lions & Coventry Insurance Services agents can help reduce the number of threats a new construction faces, and our agents can help reveal additional threats that may need to be covered by additional policies.
Builder’s risk insurance is mainly designed for new construction, rather than changes and improvements to existing buildings. That form of construction is usually covered by property insurance and does not need any additional coverage, although it’s best to talk with an agent before starting any particularly large project just to be absolutely sure it’s covered.
What does Builder’s Risk Insurance Cover?
Builder’s Risk Insurance generally covers the owner, the lending institution, the contractor(s) performing the work, and other related parties. In addition to providing coverage for damage to the building itself, most plans also cover temporary constructs (like scaffolding), materials, and equipment being used (whether it’s currently on-site or off-site). The majority of policies are written on an all-perils basis, which means that reimbursements are available for any losses except those specifically excluded.
Common exclusions from this coverage include (but are not limited to):
- The value of the land itself
- Employee theft
- Damages beyond the estimated value of the construction
- Any losses brought by law or ordinance changes
- Damage from earthquakes
- Losses from war, nuclear hazards, or actions by civil authority
As you can see, most of the exclusions are not likely to occur during the course of a normal construction project. The value of the land is the only one likely to change as new work is done, and you will likely need to account for any improvements or losses the next time your company prepares taxes.
Most policies last until the building is no longer under construction. The exact point at which this occurs can vary. It may be when certain parts of the structure are done (but finishing work, like painting, has not been completed), up to the day it opens for business, or when the contract with the construction company ends. If you’re worried about interim risks—like the building being damaged between when construction finishes and when it opens for business—talk to one of our agents and ask about extending your coverage for your Builder’s Risk Insurance policy today.
Builders risk insurance FAQ
These answers are brokerage guidance for California owners and contractors, not legal advice. Coverage depends on the submitted project, form, and underwriting. We do not promise a premium, carrier, or ranking before review. For the wider program, see our construction insurance hub. Call (916) 967-7715 or use our contact page.
What is builders risk (course-of-construction) insurance, and who usually buys it?
Builders risk — often called course-of-construction coverage — is property insurance for a building while it is being built or substantially renovated. It is written for the structure, materials, and related temporary works during the project period, not as a substitute for general liability or workers compensation. Owners, lenders, and general contractors commonly arrange it; named insureds and loss-payees should match the construction contract and loan documents. Sacramento-area and Loomis / Placer County projects are underwritten on the actual address, values, and schedule — not on a generic statewide promise.
What does builders risk typically cover on a California construction project?
Most builders risk forms address physical damage to the building under construction, including materials and supplies on site (and sometimes in transit or at temporary storage), plus temporary structures such as scaffolding when the form includes them. Policies are often written on an all-risk / special-form basis with named exclusions. Soft costs, delay-in-completion, or ordinance-or-law extras are not automatic — ask before you assume they apply. Pair this page with our construction insurance overview when you are building a full program for the GC and trades.
What is commonly excluded from builders risk coverage?
Common exclusions include the value of the land, employee theft, earthquake, flood (unless endorsed or placed separately), war and nuclear hazards, and losses caused by ordinance or law changes unless the form expressly adds that coverage. Damage beyond the reported construction values and wear-and-tear / faulty workmanship issues are also frequent friction points. Exclusions and deductibles vary by carrier and manuscript endorsement — read the specimen form for the job, do not rely on a certificate description alone.
When does builders risk start and end, and what about the gap before occupancy?
Coverage usually tracks the construction period: it starts when materials arrive or work begins under the policy terms, and it ends when the project is completed, occupied, put to its intended use, or when the contract or policy period expires — whichever the form says first. The awkward gap between substantial completion and permanent property insurance is a real exposure; ask about extending course-of-construction or binding the permanent property policy early. Bring the construction schedule, loan closing date, and intended occupancy date so the term can be matched to the job.
How does builders risk relate to GL, permanent property, and lender COI requirements?
Builders risk protects the work-in-progress; commercial general liability addresses third-party injury and property-damage claims arising from operations; permanent property takes over after the building is complete and occupied. Lenders and owners often want evidence of builders risk plus additional-insured or loss-payee wording on the certificate. Gather the exact holder name, job address, limits, and endorsement language using our California contractors COI & additional-insured checklist, then call (916) 967-7715 or use the contact form. Lions & Coventry license #0G22084 — brokerage guidance only.
How to get builders risk insurance in California
Educational steps for California contractors, owners, and lenders who need course-of-construction coverage. This is brokerage guidance from Lions & Coventry Insurance Services — not legal advice, not a premium quote, and not a ranking claim.
- Confirm who must be named — owner, GC, lender/loss payee, and any required additional interests on the course-of-construction policy (not just the GL certificate).
- Describe the project — address, construction type, hard-cost / soft-cost values, start and expected completion, renovation vs new build, and occupied vs vacant during work.
- Separate builders risk from GL and permanent property — builders risk protects the work-in-progress; commercial general liability addresses third-party injury and property-damage claims; permanent property takes over after completion and occupancy. See the construction insurance hub.
- Gather lender or owner exhibits — loss-payee wording, certificate holders, and any minimum limits or soft-cost requirements before you ask for rush paperwork.
- Call or contact a broker — reach Lions & Coventry at (916) 967-7715 or the contact form with project values and the lender exhibit so we can place coverage and issue evidence when the market supports the ask.
Related: COI & Additional Insured checklist · Workers compensation. Next step: call (916) 967-7715 or use /contact/. License #0G22084 — Citrus Heights, CA.